
How to file a property SPV's accounts and CT600 with Taxley (step by step)

Prerequisites at a glance
- Difficulty
- Intermediate
- Tools you'll use
-
- Taxley account
- Government Gateway user ID and password with Corporation Tax added
- Companies House authentication code
- Have ready
-
- Company UTR
- Company registration number (CRN)
- Rental income and property cost figures
- Mortgage interest for the year
- Year-end balance sheet figures
- Last year's accounts
In short: A property SPV is a limited company, so after each financial year it must file statutory accounts at Companies House and a Company Tax Return (CT600) with HMRC, usually online through filing software. Taxley prepares and files both for £49.95 with micro-entity accounts, sending the accounts to Companies House once the return is paid and the accounts are finished.
Take the 30-second check to see whether Taxley fits your company, or see what a property company tax return with Taxley covers.
Key facts (checked on 19 October 2026)
| Fact | Detail | Source |
|---|---|---|
| CT600 filing deadline | 12 months after the accounting period ends | GOV.UK: Company Tax Returns |
| Corporation Tax payment | 9 months and 1 day after the period ends | GOV.UK: Pay Corporation Tax |
| Accounts at Companies House | 9 months after the financial year ends | GOV.UK: Prepare and file annual accounts |
| Small profits rate, FY2025 | 19% on profits of £50,000 or less | GOV.UK: Corporation Tax rates and allowances |
| Mortgage interest in a company | A loan-relationship debit, not a property expense | HMRC manual PIM2052 |
| Close investment-holding company | No small profits rate | CTA 2010 s.18A |
This walkthrough is for a buy-to-let or commercial property company, often called an SPV (special purpose vehicle), that files micro-entity accounts for a 12-month year. Every screenshot shows Harbourview Lettings Ltd, a fictional company with one let flat, a mortgage and a loan from its director, entered in Taxley on 19 October 2026. The tax rules behind each step are explained in our Corporation Tax guide for property companies; this guide shows where each figure goes.
What do you need before you start?
You need the company's 10-digit Unique Taxpayer Reference (UTR), its company number, a Government Gateway user ID with Corporation Tax added, and the Companies House authentication code. You also need the year's rent, property costs and mortgage interest, the year-end balances and last year's accounts. HMRC posts a Corporation Tax activation code within 10 days.
| What you need | Where to find it | Where Taxley uses it |
|---|---|---|
| Company UTR, 10 digits | HMRC letters or the business tax account | Company card in Simple mode |
| Company registration number | Companies House register | Step 1 look-up |
| Government Gateway user ID and password | Business tax account with Corporation Tax added | Step 10, File with HMRC |
| Companies House authentication code | Posted to the registered office | Step 10, Companies House filing |
| Rent, costs and mortgage interest | Bank, letting agent and lender statements | Steps 4 and 6 |
| Last year's figures | Last year's accounts | Steps 4 and 5 |
Save the authentication code in Taxley's Company details, under "Companies House authentication code (optional)", before you file. Companies House posts it to the registered office, which can take up to 10 working days (GOV.UK: company authentication codes); if it's lost, see how to get a new authentication code. Last year's figures matter because accounts show both years. Taxley carries them over from a return filed with Taxley, and can fill in last year's balance sheet from machine-readable accounts at Companies House. The profit and loss figures come from your own copy, because "Companies House doesn't publish most small companies' profit and loss."
How do you file a property SPV's accounts and tax return in Taxley?
Start a new return, look up the company, choose the period and pick Property. Then fill in one page: the profit and loss account, balance sheet, mortgage interest and two questions. Review the tax computation, tick the declaration and pay, then file the CT600 with HMRC and the accounts at Companies House. The ten steps follow.
Step 1: Look up the company and choose the period
From the dashboard, press Start a new return. In "Look up your company at Companies House", type the company's name or number and press Look up. Taxley fills in the name and registration number and shows "Filled from Companies House — check the details below and continue." Under "What period does this return cover?", pick the year in "Choose the period from Companies House": the period still to file is marked Ready, and a year already filed Filed. If the dates don't match your accounts, choose "Enter dates manually instead".
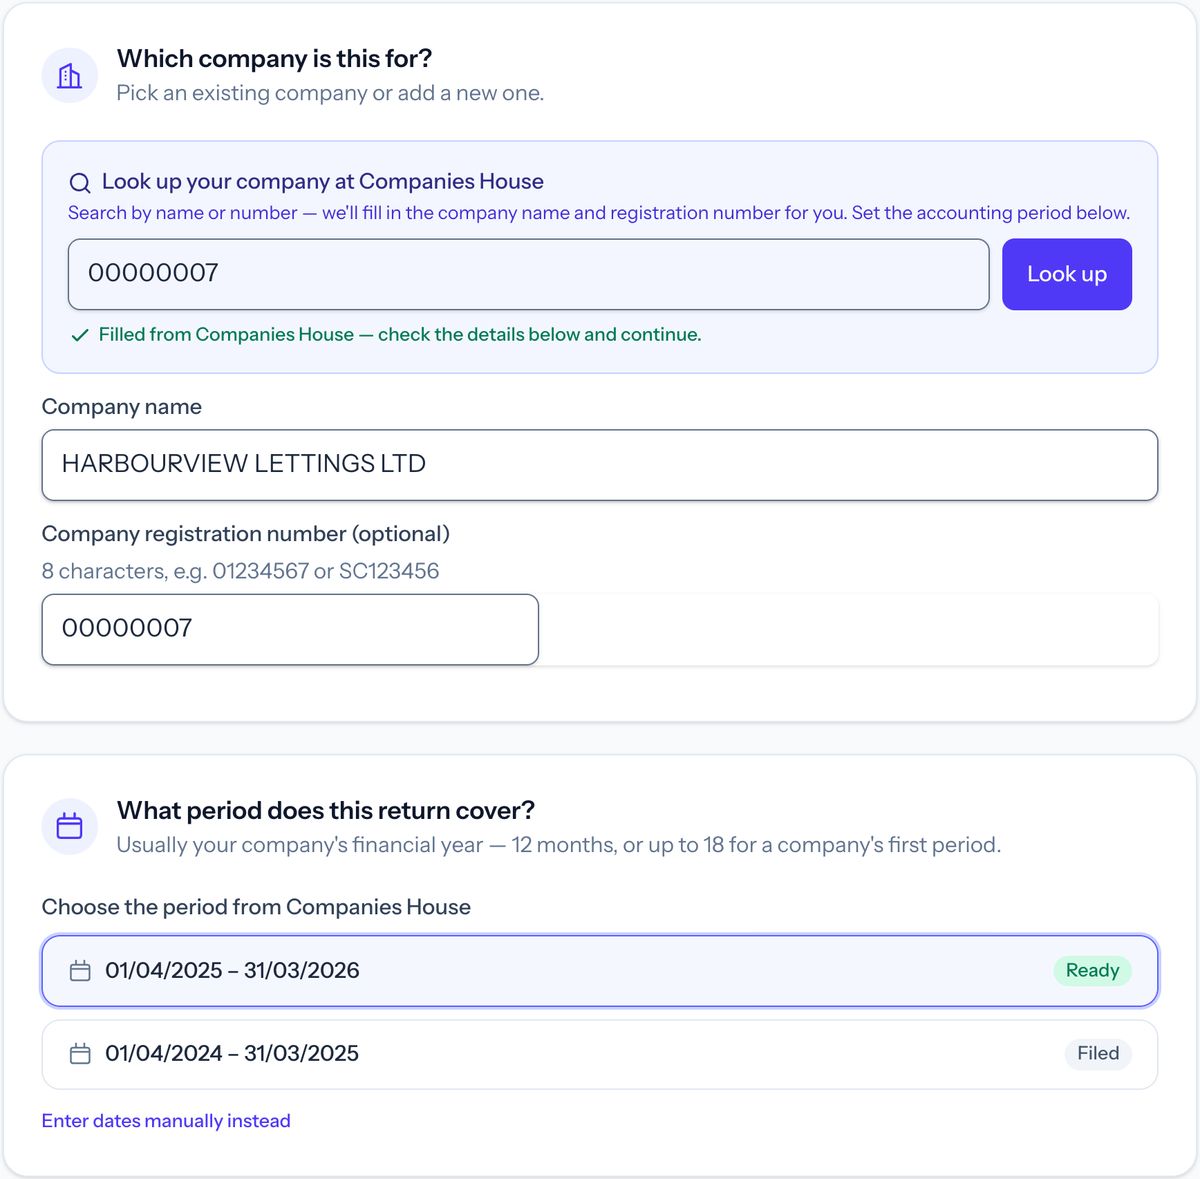 In Taxley: the Companies House look-up fills in the company and lists its periods, with the one still to file marked Ready (demo company).
Step 2: Choose Property and the type of accounts
Under "What does the company do?", choose Property, "Income from renting land or buildings". Under "Which accounts should we file?", choose CT600 + micro-entity accounts (FRS 105) or CT600 + small-company accounts (FRS 102 §1A). Micro-entity accounts keep the property at cost, because the fair value and alternative accounting rules don't apply to them (SI 2008/409 reg 3). Small-company accounts suit a company above the micro limits, or one that revalues its property. Then press Continue to my numbers.
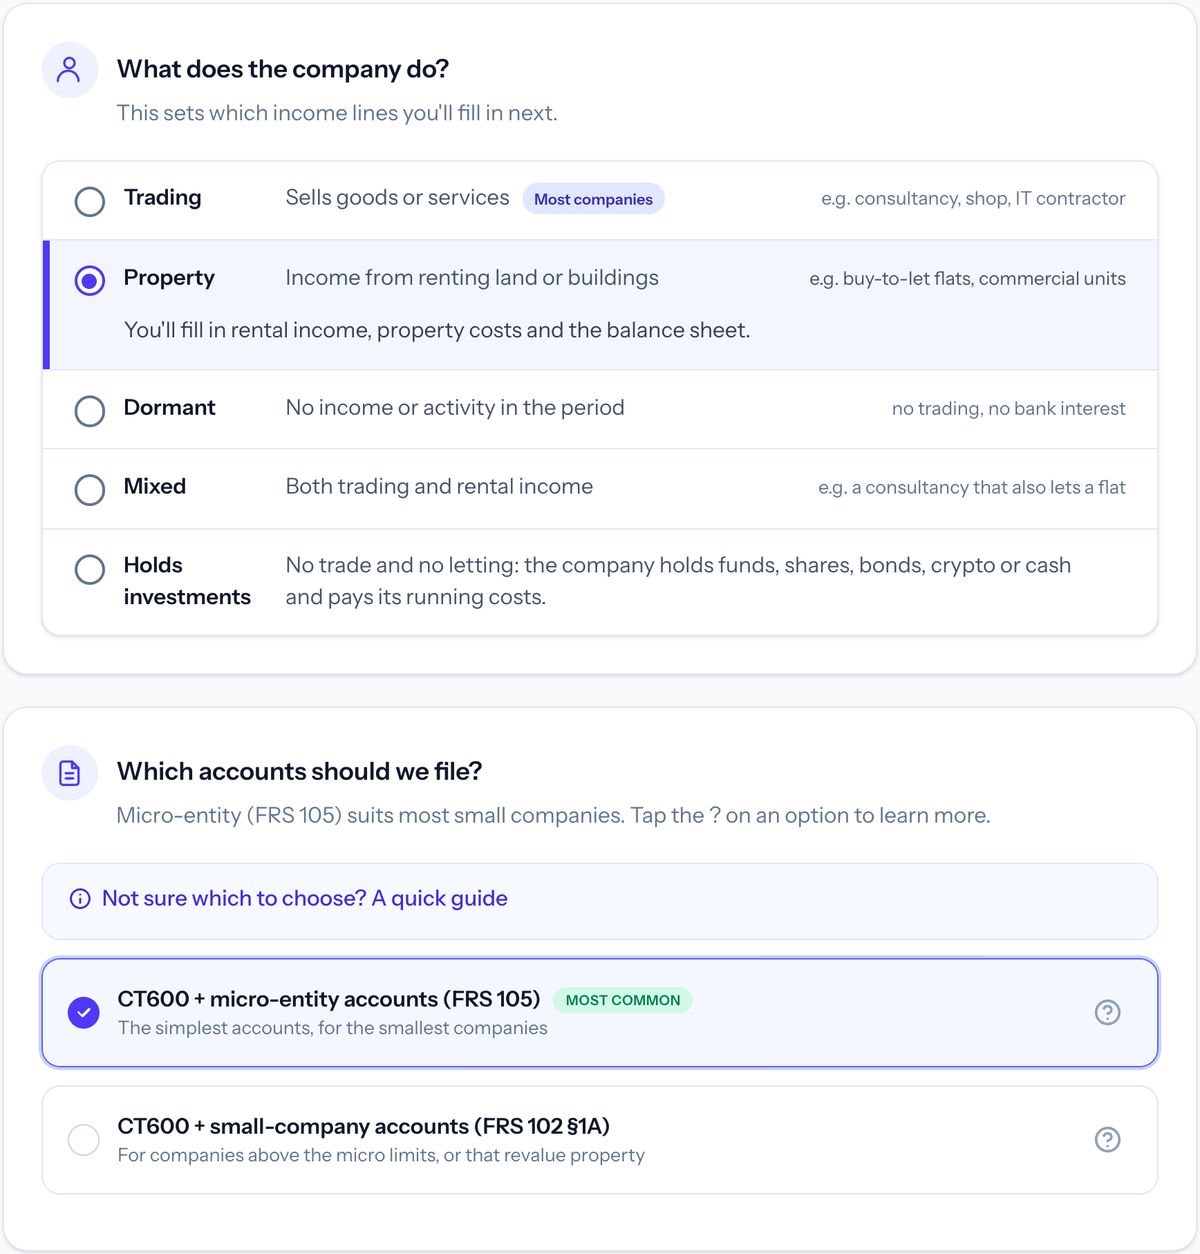 In Taxley: choosing Property sets up the rental income and property cost lines, and micro-entity accounts are selected by default (demo company).
Step 3: Answer the close investment-holding company question
A micro-entity return of 12 months or less opens in Simple mode, headed "Prepare your Corporation Tax return", unless last year's Taxley return used another mode. Check the company card and the Company UTR, then answer Close investment-holding company. A close company has that status unless it exists wholly or mainly for permitted purposes, such as letting land commercially; letting to a connected person or their relatives isn't commercial (CTA 2010 s.18N). No fits a company that "lets property only to tenants with no connection to the company". Yes means all profits pay the 25% main rate, and the return moves to the Advanced editor.
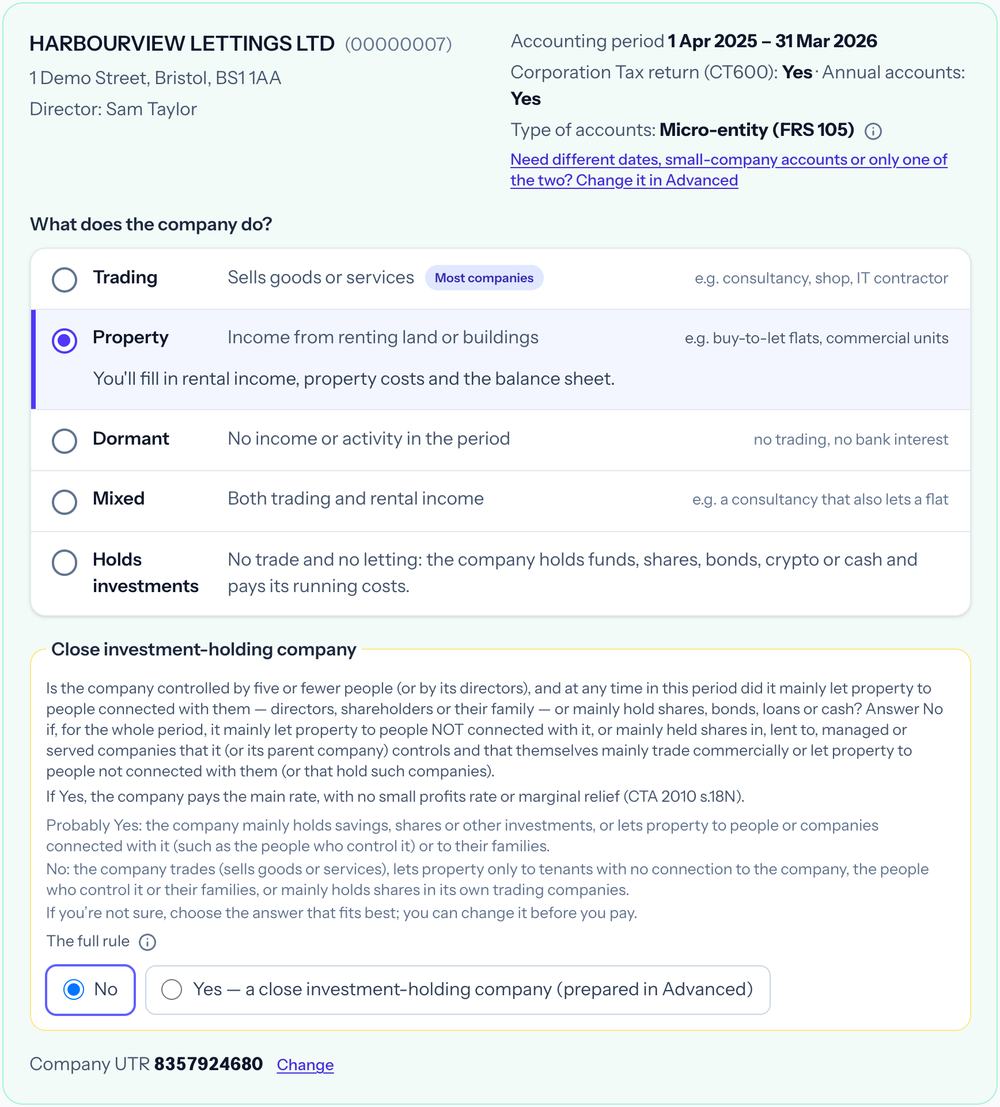 In Taxley: the company card confirms the period and accounts type, and asks every property company the close investment-holding company question (demo company).
Step 4: Enter the rent and property costs
In "Profit and loss account", enter the year's rent in Rental income and the running costs in Other charges: repairs, insurance, letting agents' fees, professional fees, rates and utilities. Leave mortgage interest out: it goes in at step 6, and the Loan and mortgage interest line then shows it here, read-only. Enter last year's figures in the right-hand column, because "accounts must show both years". Harbourview's rent is £36,000, and its Other charges of £6,900 are agent fees of £3,600, repairs of £2,400 and insurance of £900. Import a trial balance file (CSV/Excel) loads the figures instead.
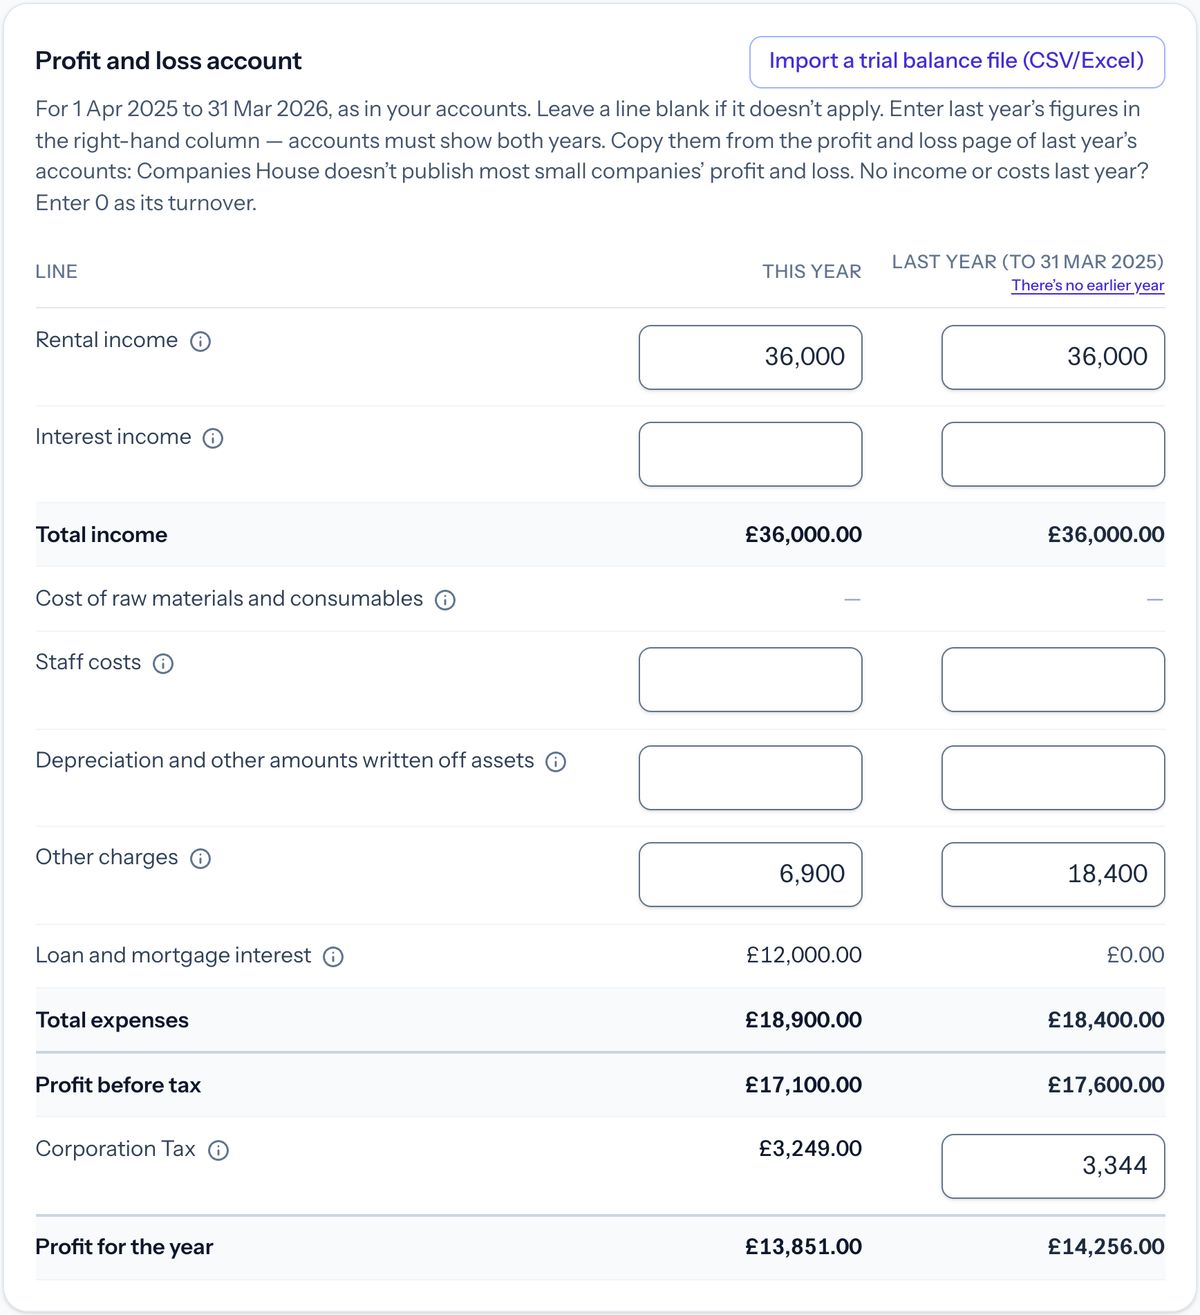 In Taxley: property costs go in one Other charges box, and the mortgage interest line fills in from the Corporation Tax section (demo company).
Step 5: Fill in the balance sheet
In "Balance sheet", enter the property in Fixed assets at cost, because "micro-entity accounts (FRS 105) don't allow revaluation". Put the bank balance in Total current assets, a director's loan repayable on demand in Creditors due within one year, and the mortgage in Creditors due after more than one year. Taxley works out Corporation Tax payable and Retained earnings, and the badge reads "Balances" once the sheet adds up. Harbourview shows the flat at £420,000, cash of £8,000, the director's £110,000 loan and the £300,000 mortgage.
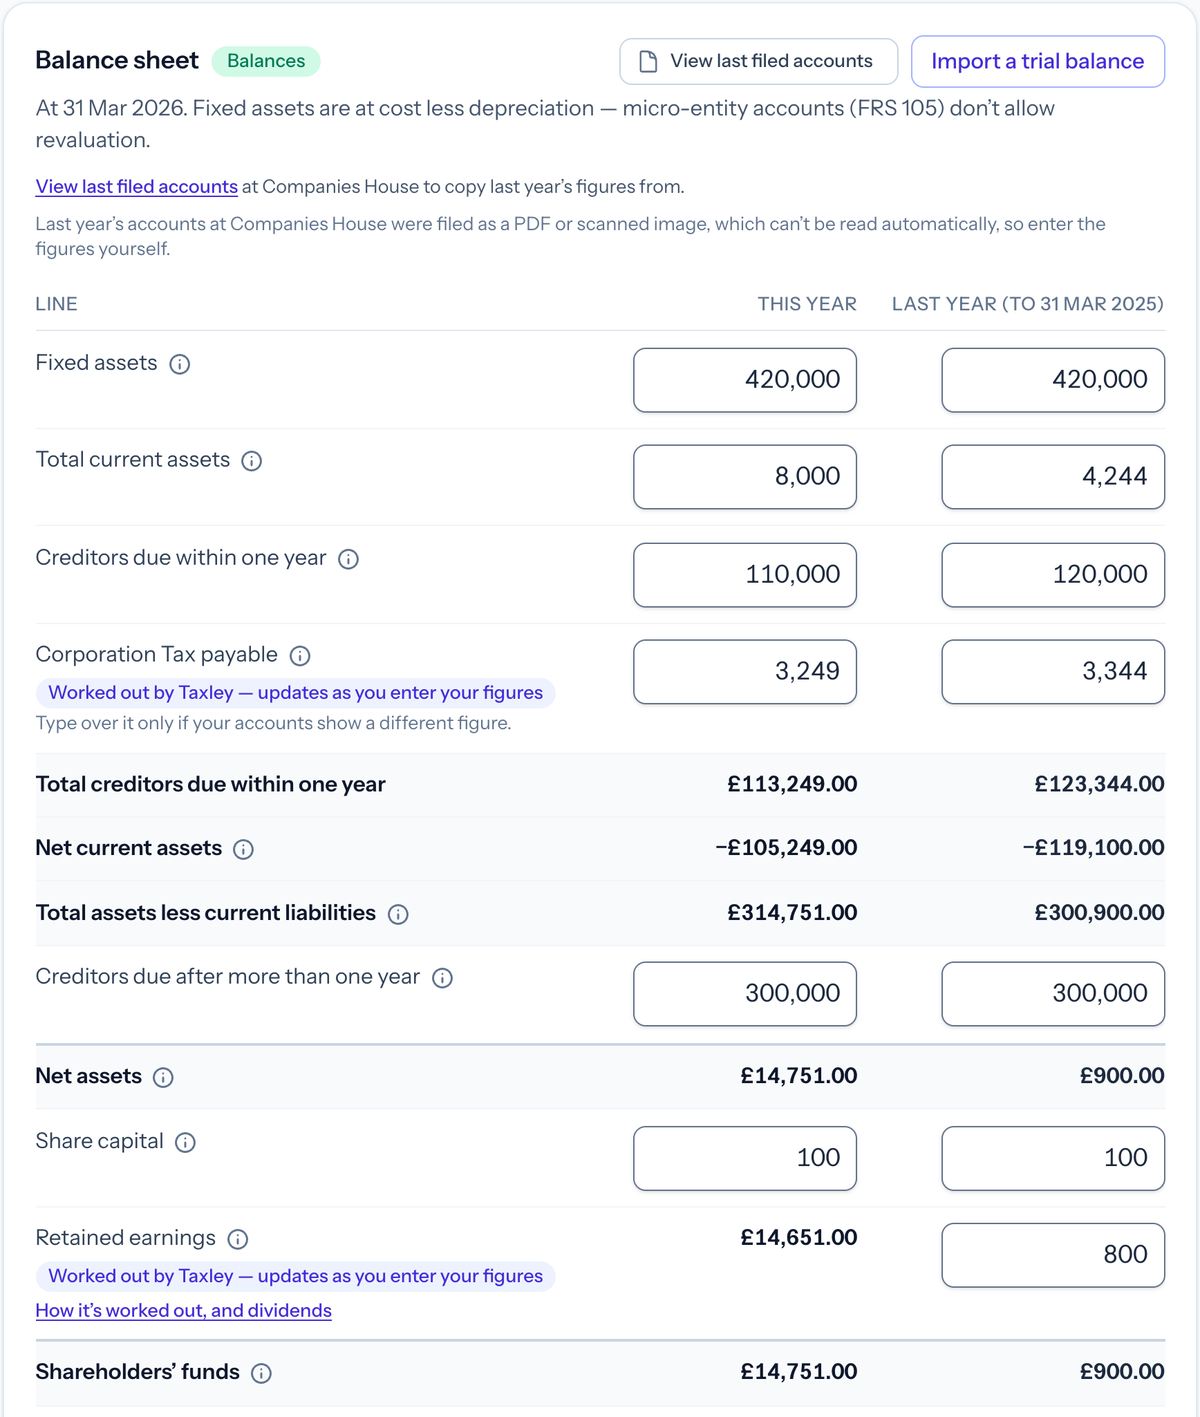 In Taxley: the property stays at cost, and Corporation Tax payable and retained earnings are worked out for you (demo company).
Step 6: Enter the mortgage interest under Specialist adjustments
In the "Corporation Tax" section, open Specialist adjustments and enter the year's interest in Loan and mortgage interest paid: £12,000 for Harbourview. For a company, interest isn't an expense of the property business; it is relieved under the loan relationship rules (HMRC manual PIM2052). Leave Associated companies at 0 unless other companies are under the same control. Open "Property losses" only for an unused loss from an earlier year, and "Capital allowances" only for equipment the company bought. The section then shows the tax and "Pay HMRC by 1 January 2027".
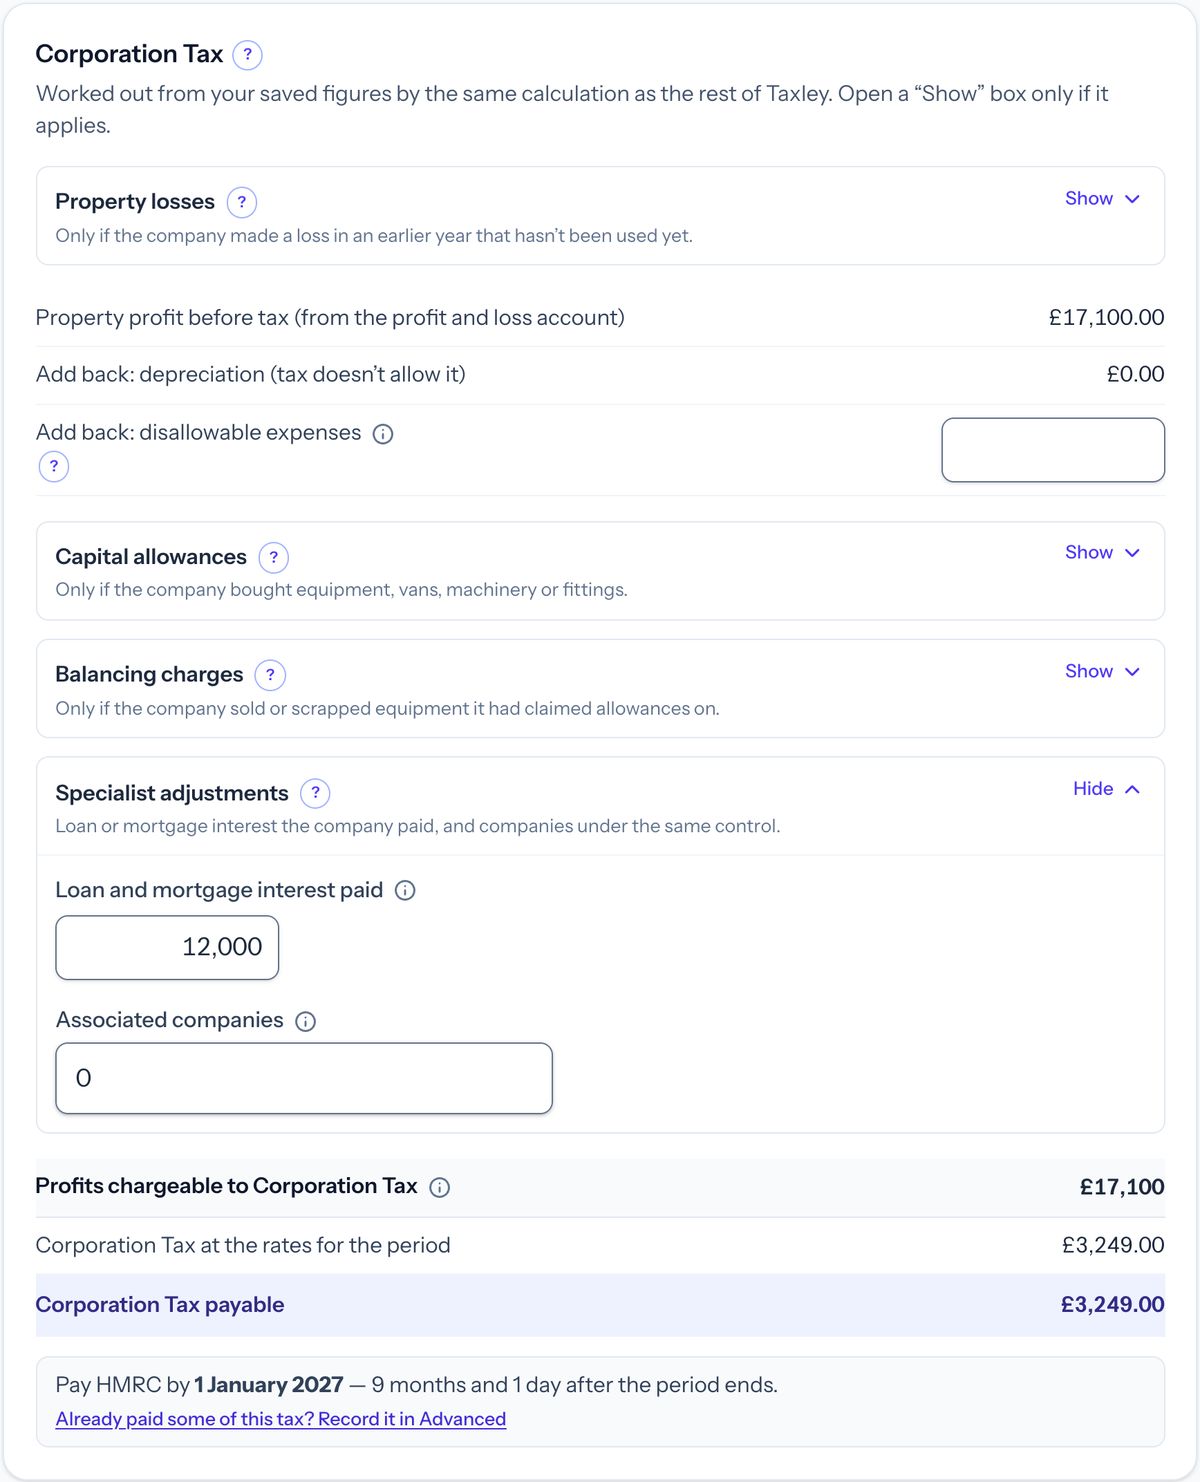 In Taxley: mortgage interest is entered once, under Specialist adjustments, and the tax and payment date follow from it (demo company).
Step 7: Answer the directors' loans question
Under "Accounts information", check the principal activity, the approval date and the average number of employees, then answer "Did a director borrow from, or owe money to, the company this year?". A director who lent the company money answers No: section 455 tax arises when a close company makes a loan or advance to a participator (CTA 2010 s.455; HMRC manual CTM61505), not the other way round. Harbourview owes its director £110,000, so it needs no CT600A. Interest paid to a director has Income Tax deducted and reported on form CT61 (GOV.UK), which Taxley doesn't file.
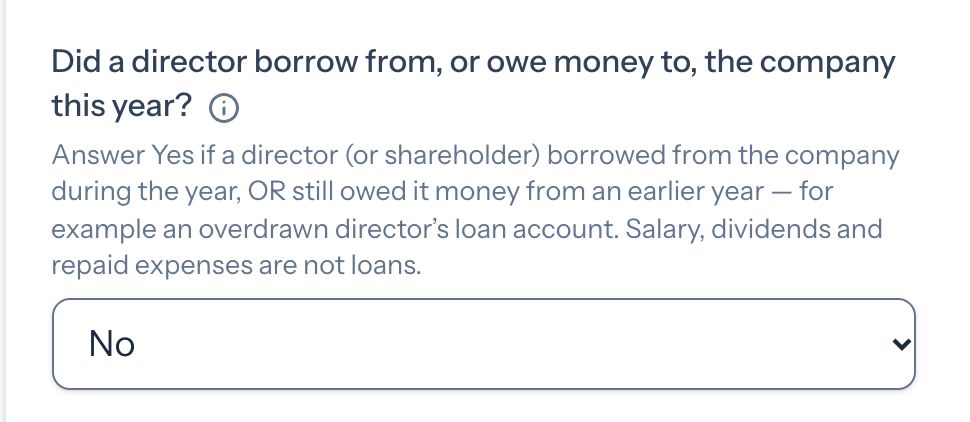 In Taxley: a loan from the director to the company is answered No, because the company owes the director, not the other way round (demo company).
Step 8: Review the tax computation
Press Review and pay. The review page lists "What's left before you can pay", then the figures. Under "Corporation Tax computation", open Technical details to see the CT600 boxes. Harbourview's property business profit is £29,100 in box 190, before interest. The £12,000 of interest is a non-trading deficit in box 795, set against the same period's profits in box 260, leaving taxable total profits of £17,100 at the 19% small profits rate. HMRC's Company Tax Return guide explains each box.
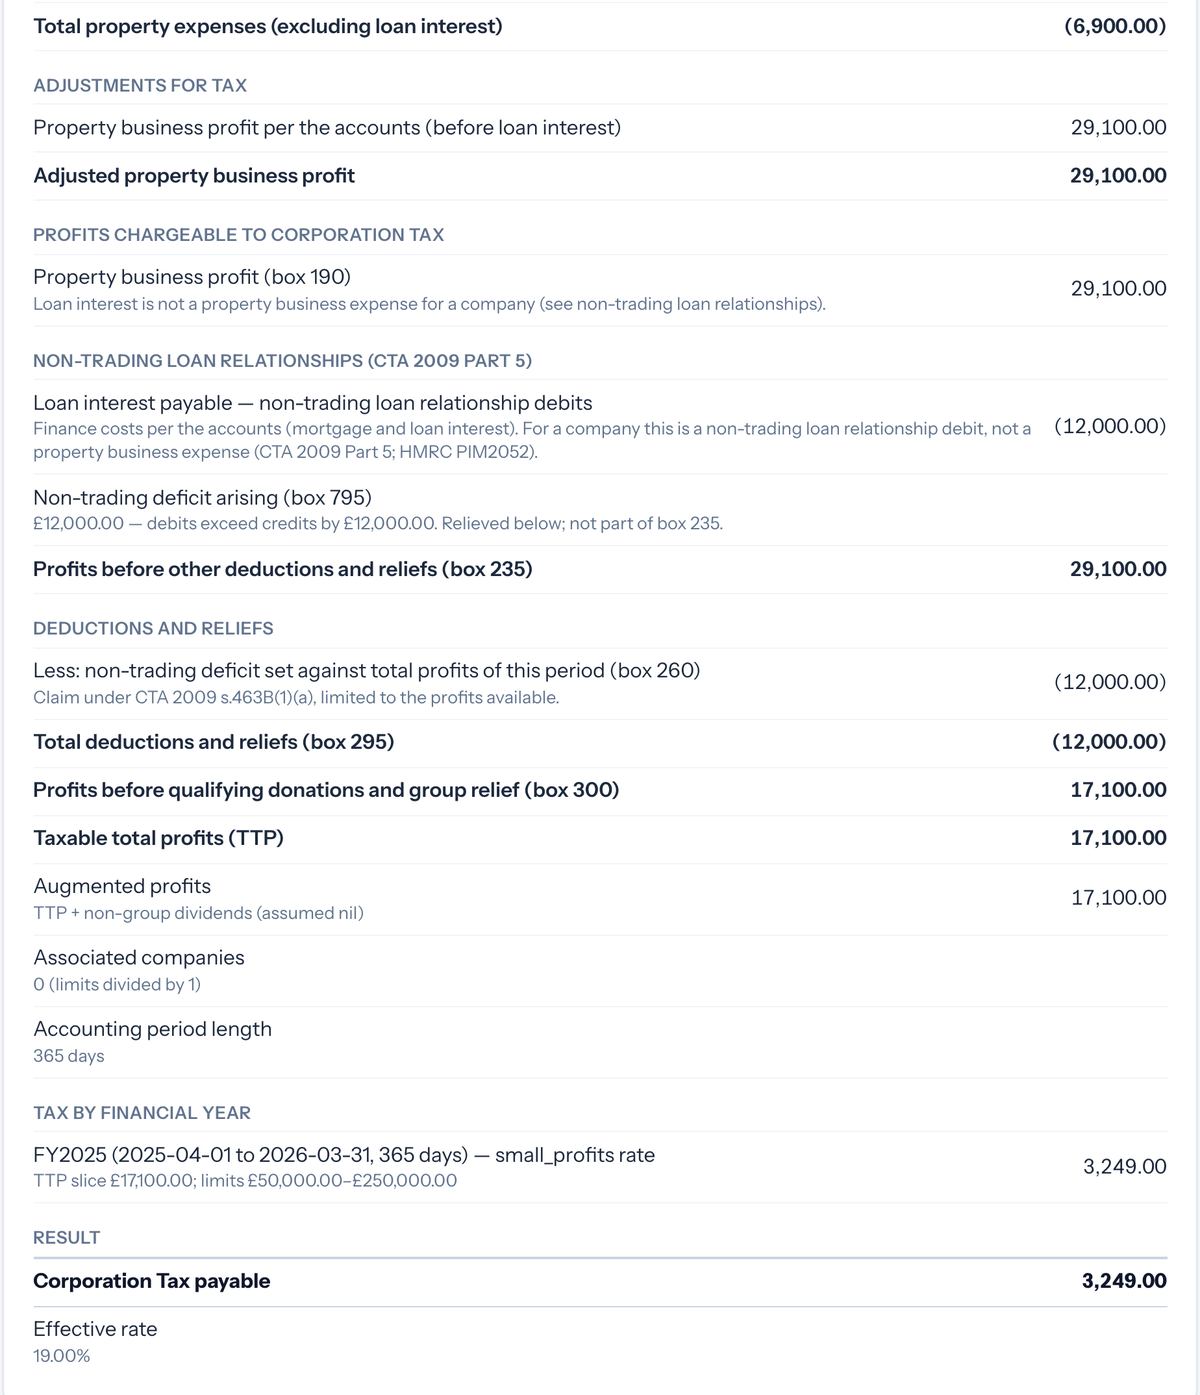 In Taxley: the computation treats the mortgage interest as a loan-relationship deficit, set against the property profit to leave £17,100 taxable (demo company).
Step 9: Tick the declaration and pay
In "Confirm and pay", check the "Declaration": who makes it, the "Director signing the accounts" and the "Date the accounts were approved", which is today unless you change it. Read the confirmation before you tick it: Taxley applies only the tax adjustments you enter, including any corporate interest restriction, which it doesn't work out. Then pay the filing fee. You pay before you file, and the fee also covers filing the accounts at Companies House. The company's Corporation Tax is paid to HMRC separately, by its own deadline.
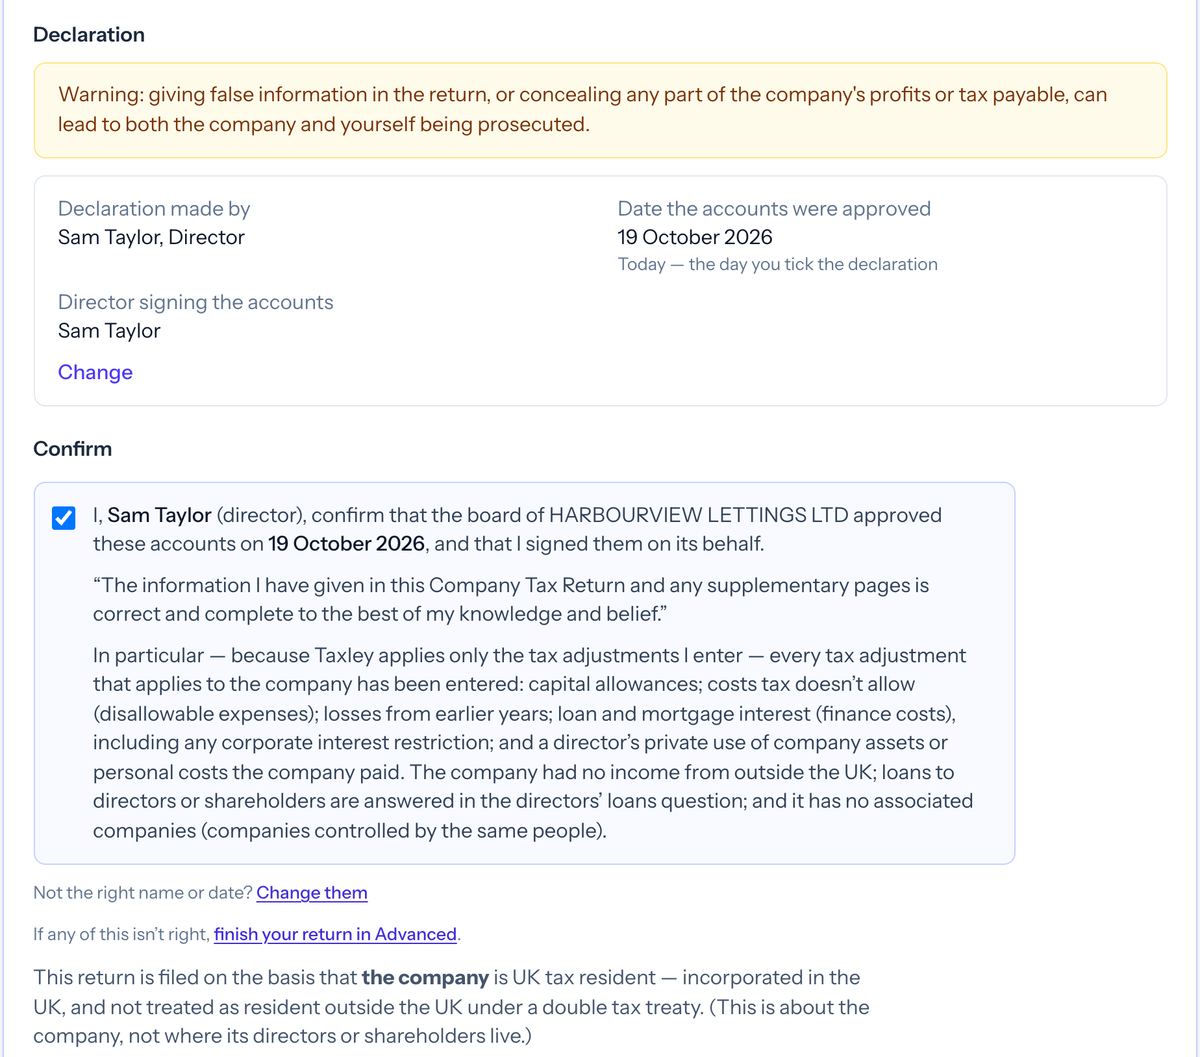 In Taxley: the director confirms the accounts approval and the CT600 declaration with one tick before paying (demo company).
Step 10: Check the Gateway sign-in, then file with HMRC and Companies House
Under "HMRC submission", go through "Before you file, check:", including that Corporation Tax is listed in the company's business tax account. Enter the company's own Government Gateway user ID and password, the account enrolled for Corporation Tax, and press File with HMRC. Taxley "never keeps your password". Then, under "Companies House — accounts filing", press File accounts at Companies House. That sends the accounts with the company's authentication code, as "a real, legally effective filing". Check each result as it comes back, and keep both.
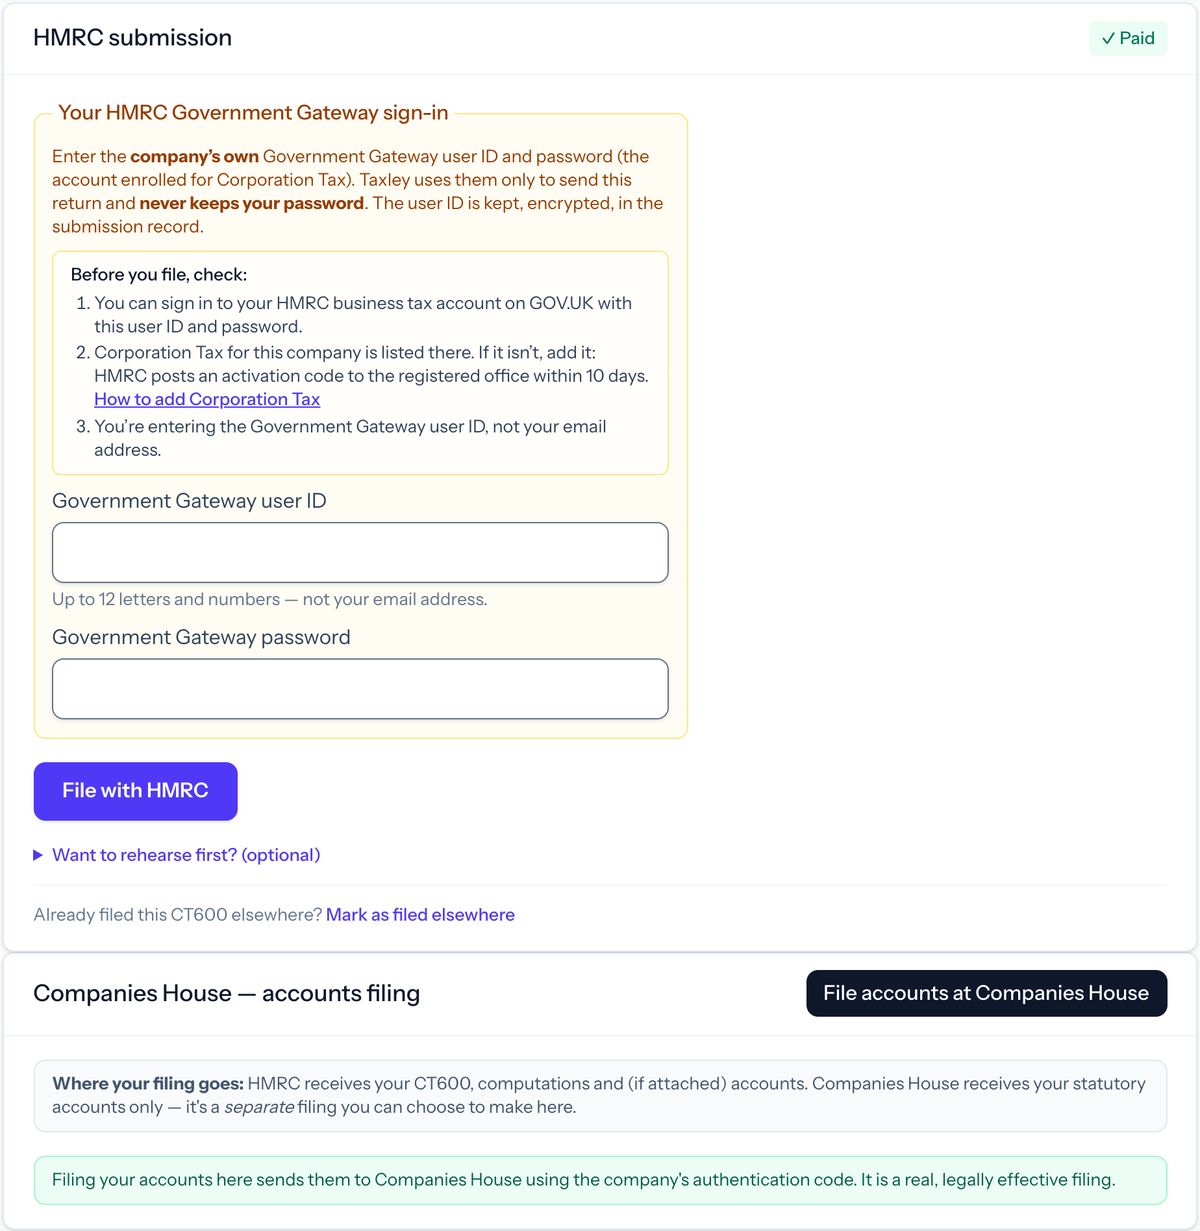 In Taxley: once the return is paid, you file the CT600 with the company's Gateway sign-in, then send the accounts to Companies House from the same page (demo company).
How much Corporation Tax does a property SPV pay on £36,000 of rent?
Harbourview Lettings Ltd, the fictional SPV in the screenshots, pays £3,249. Rent of £36,000 less £6,900 of costs leaves a property profit of £29,100. The £12,000 of mortgage interest is a loan-relationship deficit set against it, so £17,100 is taxed at the 19% small profits rate, payable 9 months and 1 day after the year ends.
| Line | Amount | Where it goes |
|---|---|---|
| Rental income | £36,000 | Profit and loss account |
| Agent fees, repairs and insurance | £6,900 | Other charges |
| Property business profit | £29,100 | CT600 box 190 |
| Mortgage interest | £12,000 | Deficit in boxes 795 and 260 |
| Taxable total profits | £17,100 | CT600 box 315 |
| Corporation Tax at 19% | £3,249 | CT600 box 440 |
| Profit after tax | £13,851 | Profit and loss account |
The example assumes a 12-month period from 1 April 2025 to 31 March 2026, no associated companies and no other income. For the financial year 2025, profits of £50,000 or less pay 19% (GOV.UK: rates and allowances), so £17,100 × 19% = £3,249, payable by 1 January 2027. Setting the deficit against the same period's profits is a claim; HMRC's manual also covers carrying a deficit back or forward (HMRC manual CFM32060). The accounts show the interest within Other charges, and retained earnings rise from £800 to £14,651. As a close investment-holding company, the same company would pay the 25% main rate: £17,100 × 25% = £4,275.
When are a property SPV's accounts and CT600 due?
For a 12-month year after the first, the accounts are due at Companies House 9 months after the year ends, the Corporation Tax 9 months and 1 day after it, and the CT600 12 months after it (GOV.UK: prepare and file annual accounts). The tax and the accounts therefore fall due before the return itself.
| Deadline | Year to 31 March 2026 | Rule |
|---|---|---|
| Accounts at Companies House | 31 December 2026 | 9 months after the year end |
| Corporation Tax paid to HMRC | 1 January 2027 | 9 months and 1 day after |
| CT600 filed with HMRC | 31 March 2027 | 12 months after the period ends |
First accounts usually cover more than 12 months, and a Company Tax Return can't, so a company's first year can need two returns (GOV.UK: first accounts and tax return). A late return costs money even when no tax is due: HMRC charges £200 one day late and another £200 at three months (GOV.UK: late filing penalties). Companies House has its own late filing penalties for accounts. The Corporation Tax deadline calculator works out all three dates for any year end.
What does Taxley not do for a property SPV?
Taxley doesn't revalue property in micro-entity accounts, calculate deferred tax, work out a corporate interest restriction or file the CT61. It doesn't file Self Assessment, so it isn't for rental income you hold personally. Simple mode also puts all property costs in one "Other charges" box; the Advanced editor has separate lines.
- Revaluation: micro-entity accounts hold the property at cost. For fair value, choose small-company accounts (FRS 102 §1A) in the Advanced editor; see cost or fair value for investment property.
- Deferred tax: Taxley doesn't calculate it. Small-company accounts have a "Deferred tax charge/(credit)" line for a figure you work out yourself.
- Simple mode's scope: micro-entity accounts for 12 months or less. Small-company accounts, "Mixed" trading and rental income, a close investment-holding company or a longer period use the Advanced editor, which has separate lines such as "Repairs & maintenance", "Insurance" and "Agent / management fees", with mortgage interest on "Interest payable".
- Personal lettings: property you own yourself is reported on your own Self Assessment tax return, which Taxley doesn't file.
- Companies House: Taxley files the accounts there, except accounts you uploaded instead of Taxley's, first accounts whose period doesn't start on the incorporation date, accounts for a period Companies House already has that weren't filed through Taxley, and a community interest company's accounts. It doesn't file the confirmation statement.
- Residence and status: the return is filed on the basis that the company is UK tax resident, and Taxley doesn't support non-resident companies or companies in liquidation or administration.
- Advice: Taxley is software, not an accountant or tax agent. It doesn't give tax advice or pay the company's Corporation Tax.
What does Taxley file for a property SPV, and what does it cost?
Taxley (taxley.co.uk), UK online software that prepares and files the Company Tax Return (CT600) with HMRC and the annual accounts with Companies House, charges £49.95 per return with micro-entity accounts or £139 with small-company accounts. The fee covers filing the accounts at Companies House, live since 28 September 2026, once the return is paid and the accounts are finished.
You see the Corporation Tax before you pay, and you pay one fee per return when you file, with no subscription. If HMRC rejects a return, correcting it and sending it again costs nothing extra, and amending a return filed with Taxley is included. Taxley works from the figures you enter and isn't tax advice, so review them before you file, ideally with a qualified adviser. Check whether Taxley fits your company, or compare the fees for each type of return.
Figures and screens checked on 19 October 2026 against the linked GOV.UK and legislation pages and Taxley's product. Harbourview Lettings Ltd is fictional. This is general information, not advice on your company's tax position.
Frequently asked questions
Can I file my SPV's accounts and tax return myself?
Yes. A director can prepare and file the company's own CT600 and accounts with filing software. You remain responsible for the figures and the declaration, so take advice on anything unusual, such as connected tenants or large loans. Our guide to filing a CT600 yourself covers the general steps for any company.
Does an SPV that made a loss still file a CT600?
Yes. GOV.UK says a company must still send a return if it makes a loss or has no Corporation Tax to pay. An unused property business loss is carried forward to the next period (CTA 2010 s.62), and Simple mode has a "Property losses" box for it.
Can a property company deduct its mortgage interest?
Generally yes, but not as a property expense. A company gets relief for loan interest under the loan relationship rules (HMRC manual PIM2052), while individual landlords of homes get finance-cost relief only at the basic rate of Income Tax. Our property company Corporation Tax guide explains the difference.
What if my SPV owes me money?
Then you lent the company money. Show the balance as a creditor and answer No to the directors' loans question, because section 455 tax arises on loans the company makes to participators, not loans they make to it (CTA 2010 s.455). See who owes whom on a director's loan account.
Does a new SPV need to file before it buys a property?
A new SPV that hasn't started its business and has no income, such as rent or bank interest, is usually dormant for Corporation Tax. It still files a return if HMRC sends a notice to deliver one, and its Companies House accounts are a separate filing. See our dormant company tax return guide.
Can I use Taxley for buy-to-let property I own personally?
No. Rental income from property you own yourself is reported on your own Self Assessment tax return above GOV.UK's thresholds, and Taxley doesn't file Self Assessment. Taxley files limited companies' Company Tax Returns and accounts. See Making Tax Digital for landlords for the personal rules.
People also ask
Related guides

Corporation Tax for a property (rental) company
14 min read →

How to file a CT600 yourself: step-by-step guide
16 min read →

Director's loan account: does the company owe you?
6 min read →

Micro-entity accounts: contents, notes and example
18 min read →

Company accounts FAQs: Companies House questions answered (2026)
15 min read →

Disallowable expenses for Corporation Tax: adjustments explained
19 min read →
Ready to file your Company Tax Return?
Confirm support for your accounting period, accounts and any supplementary pages before paying. Taxley support can answer software questions, not provide a tax opinion.
Questions about your period or accounts? Ask about software support